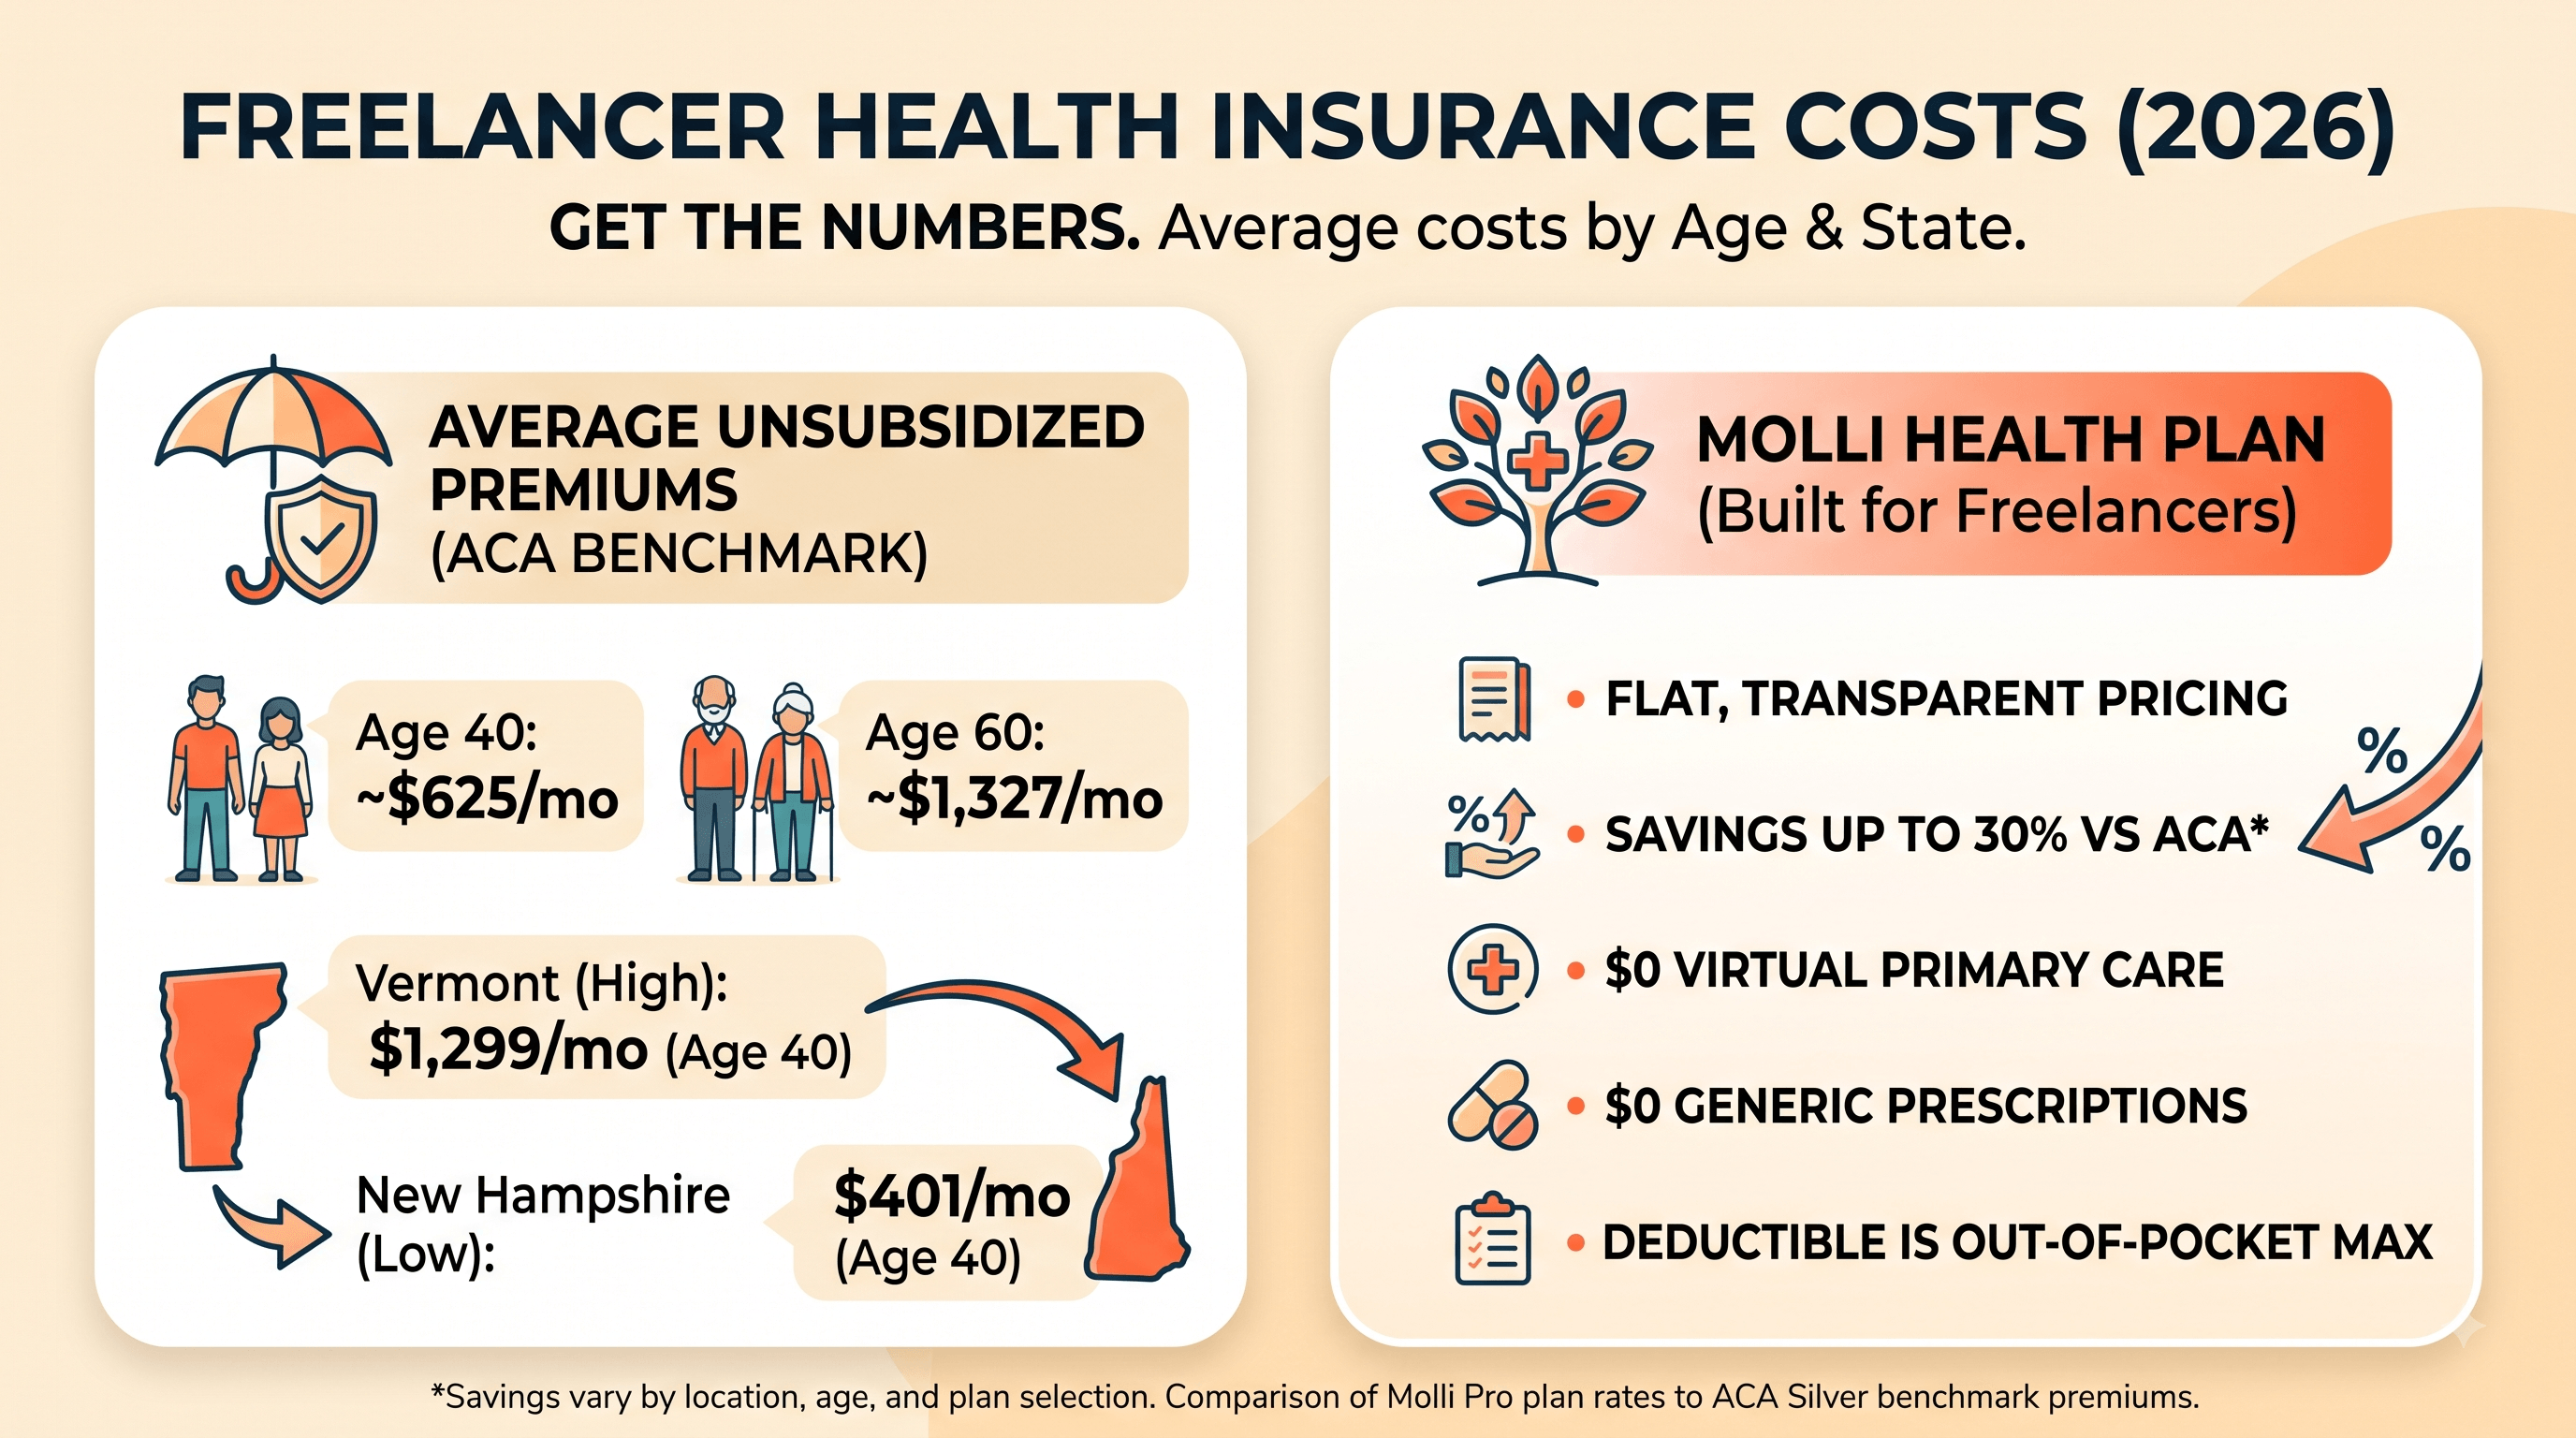
Freelancer Health Insurance Cost by Age and State 2026
Average Health Insurance Cost for Freelancers by Age and State (2026)
If you are a freelancer buying your own coverage, here is the number to anchor on: the average unsubsidized benchmark premium in 2026 is about $625 per month for a 40-year-old, per KFF, up about 26% from 2025. Where you land against that average depends almost entirely on two things you cannot control: your age and your state.
Here are the real numbers for both.
Average monthly premium by age (2026)
The ACA limits insurers to charging a 64-year-old no more than 3 times what a 21-year-old pays, along a federal age curve. Applying that curve to the $625 national benchmark average gives the typical unsubsidized monthly premium by age:
| Age | Average monthly premium |
|---|---|
| 21 | $489 |
| 25 | $491 |
| 30 | $555 |
| 35 | $598 |
| 40 | $625 |
| 45 | $706 |
| 50 | $873 |
| 55 | $1,090 |
| 60 | $1,327 |
| 64 | $1,467 |
Two takeaways. Premiums are essentially flat through your twenties, then climb steeply: the jump from 45 to 55 is about $384 per month, or $4,600 per year. And these are single-person rates; family coverage stacks each member's age rate.
Average monthly premium by state (2026, age 40)
KFF's 2026 averages for the benchmark Silver plan, ranked from most to least expensive:
| Rank | State | Monthly premium |
|---|---|---|
| 1 | Vermont | $1,299 |
| 2 | Wyoming | $1,090 |
| 3 | West Virginia | $1,073 |
| 4 | Alaska | $1,032 |
| 5 | Connecticut | $870 |
| 6 | New York | $817 |
| 7 | Arkansas | $774 |
| 8 | Tennessee | $711 |
| 9 | Nebraska | $710 |
| 10 | Maine | $709 |
| 11 | Montana | $692 |
| 12 | Delaware | $691 |
| 13 | Florida | $683 |
| 14 | Kansas | $670 |
| 15 | Mississippi | $662 |
| 16 | Texas | $661 |
| 17 | South Dakota | $655 |
| 18 | Illinois | $646 |
| 19 | Louisiana | $646 |
| 20 | Alabama | $645 |
| 21 | Utah | $640 |
| 22 | North Carolina | $638 |
| 23 | New Mexico | $623 |
| 24 | Georgia | $615 |
| 25 | Washington | $612 |
| 26 | Wisconsin | $611 |
| 27 | District of Columbia | $610 |
| 28 | Missouri | $605 |
| 29 | Oklahoma | $604 |
| 30 | Kentucky | $590 |
| 31 | Pennsylvania | $572 |
| 32 | California | $570 |
| 33 | North Dakota | $570 |
| 34 | South Carolina | $564 |
| 35 | Colorado | $557 |
| 36 | New Jersey | $545 |
| 37 | Oregon | $543 |
| 38 | Hawaii | $541 |
| 39 | Arizona | $532 |
| 40 | Michigan | $523 |
| 41 | Ohio | $513 |
| 42 | Rhode Island | $506 |
| 43 | Iowa | $501 |
| 44 | Nevada | $497 |
| 45 | Massachusetts | $494 |
| 46 | Idaho | $490 |
| 47 | Indiana | $474 |
| 48 | Virginia | $455 |
| 49 | Minnesota | $448 |
| 50 | Maryland | $414 |
| 51 | New Hampshire | $401 |
The spread is enormous: a 40-year-old freelancer in Vermont pays more than 3 times what one in New Hampshire pays for a comparable benchmark plan.
How to read these numbers
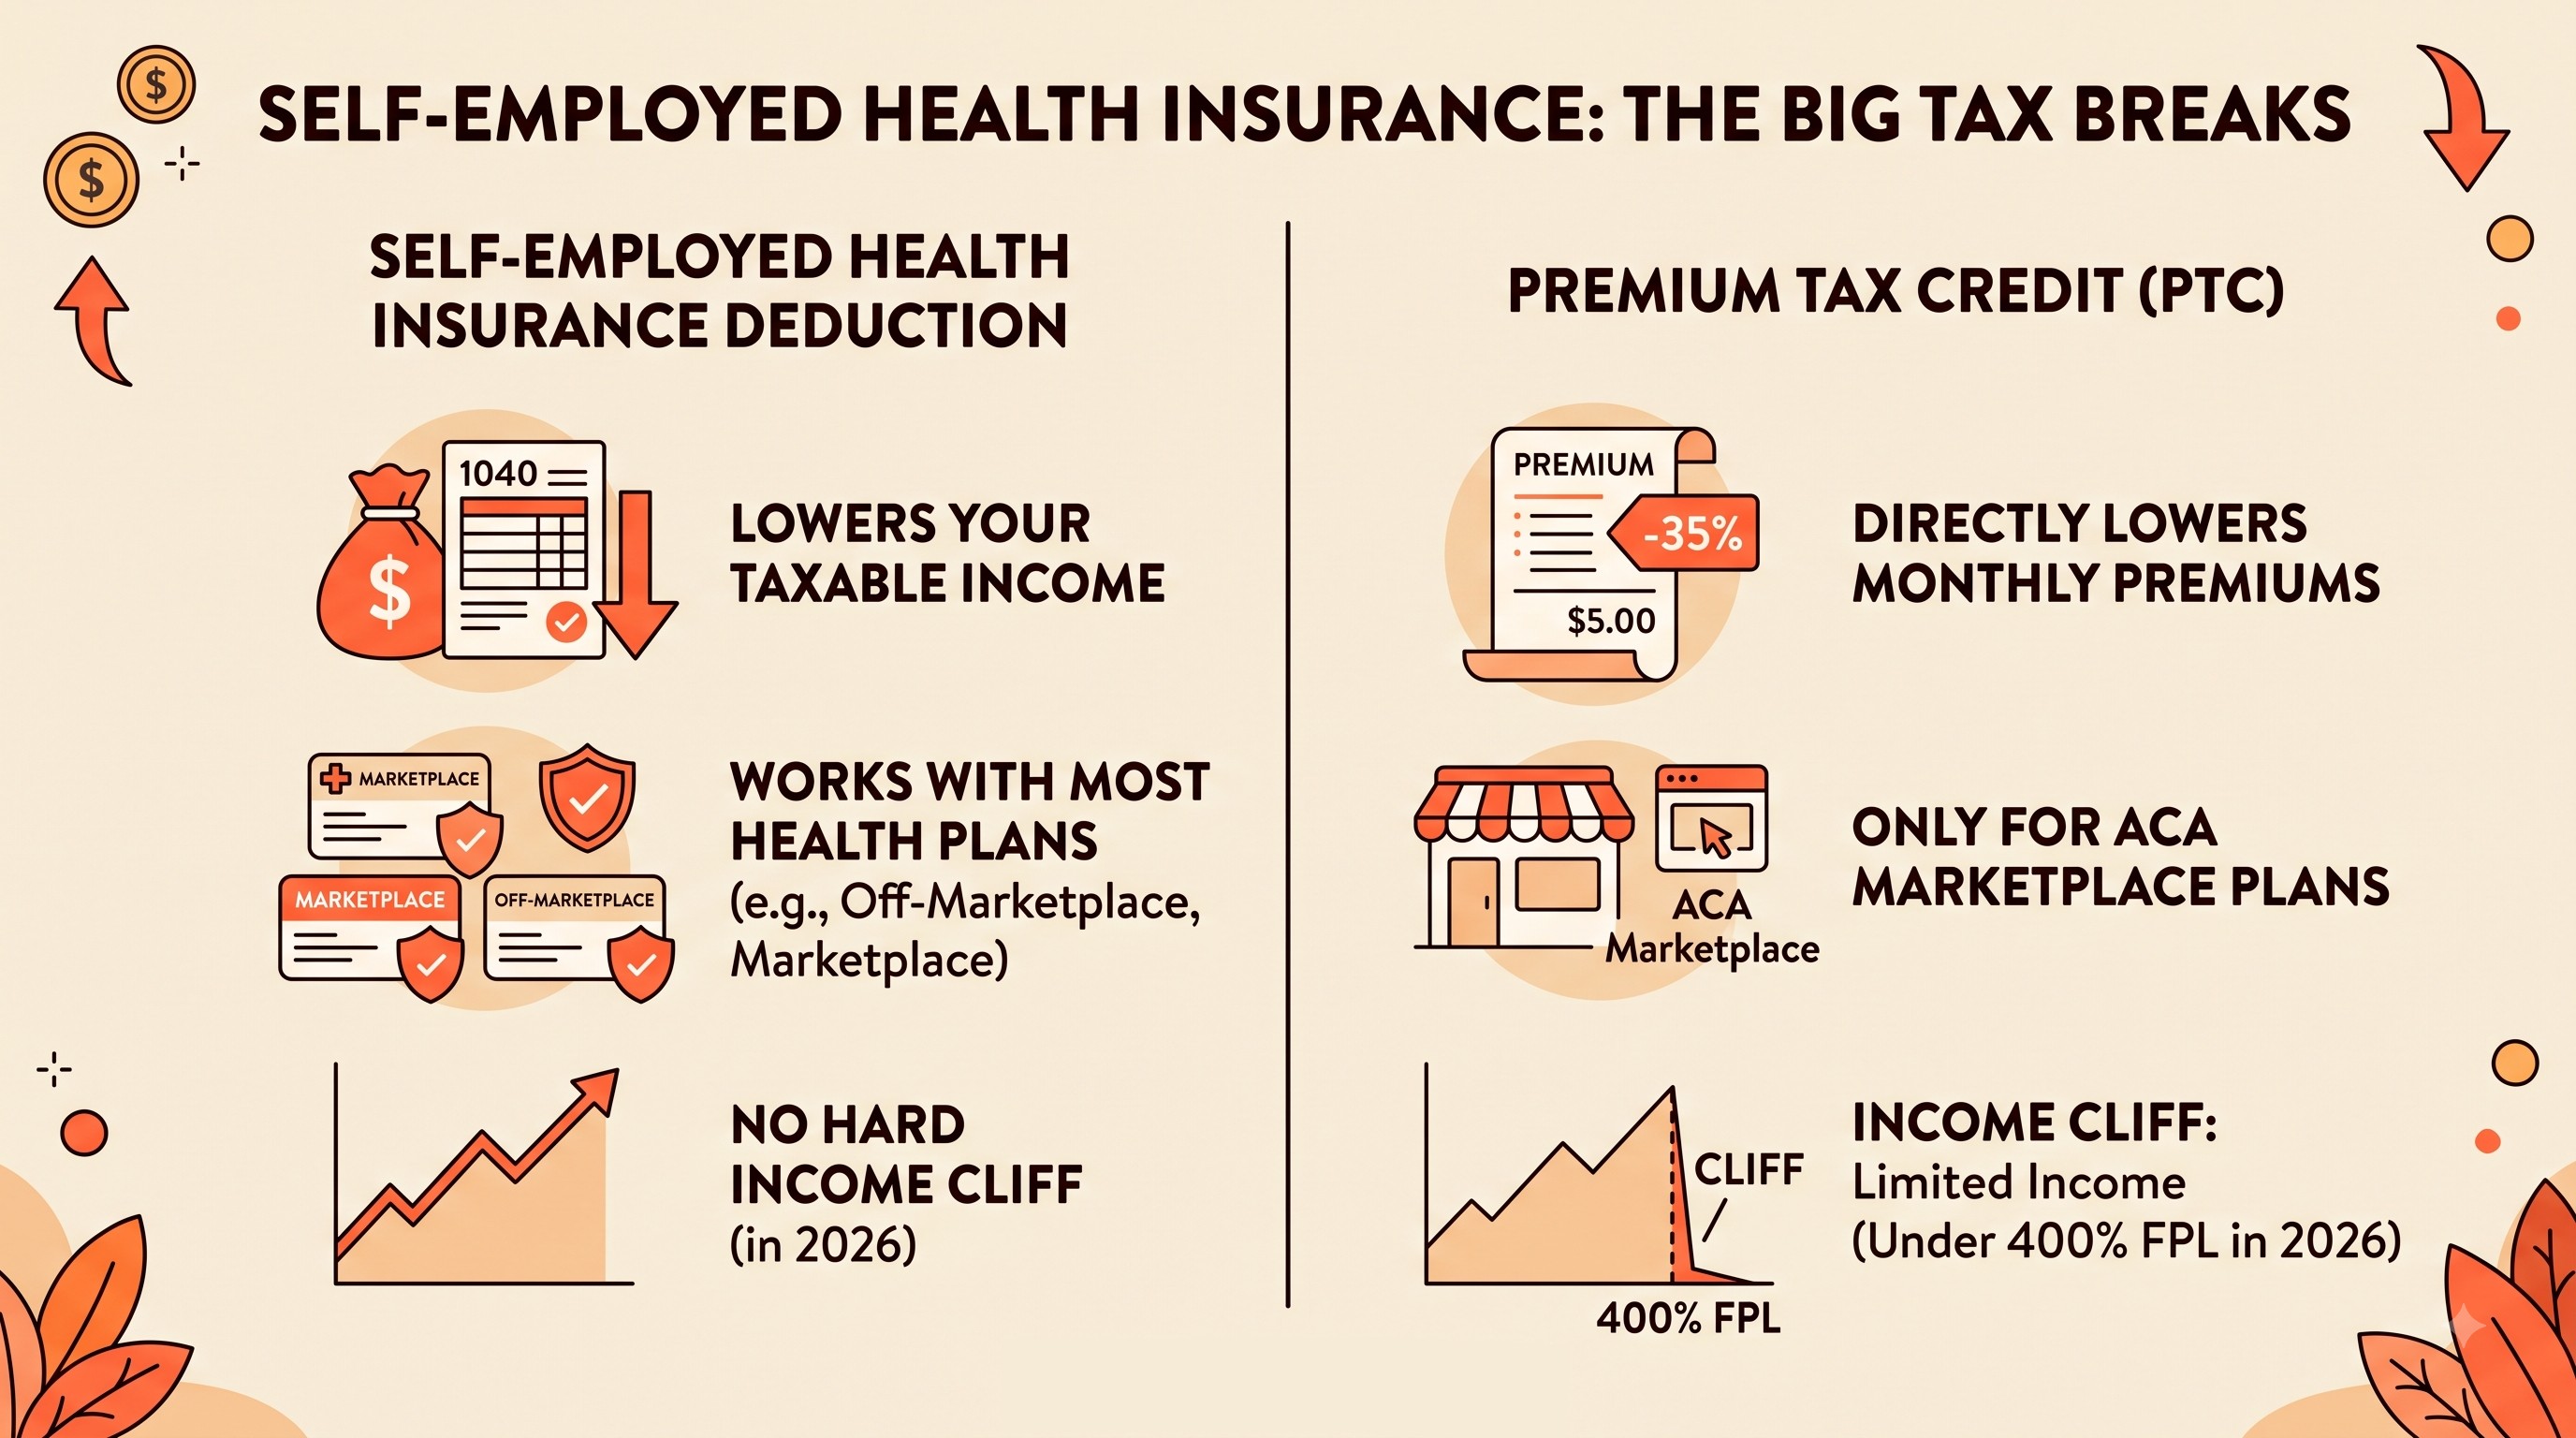
They are sticker prices. These are unsubsidized premiums. For 2026, if your income is above 400% of the federal poverty level (about $62,600 for a single person), the sticker price is your price, because the enhanced subsidies expired at the end of 2025 and the income cutoff is back. See our breakdown of the subsidy cliff and what it means for your bill.
Premiums are only half your cost. The benchmark Silver plan still carries a deductible, copays, and coinsurance on top of the premium. Your real annual exposure is premium plus out-of-pocket maximum.
Methodology note: state figures are KFF's 2026 average second-lowest-cost Silver ("benchmark") premiums for a 40-year-old, weighted by county plan selections. Age figures apply the federal ACA age-rating curve to the national average. Your quote will vary by county, plan, and tobacco status.
Where Molli fits
Molli is an ACA-compliant major medical plan built for freelancers, contractors, and 1099 workers, sold off the marketplace with flat, transparent pricing that can save up to 30% vs. ACA marketplace plans¹. Every Molli plan includes $0 virtual primary care and $0 generic prescriptions through Vitable, preventive care covered 100% before the deductible, and a simple structure where your in-network deductible is also your out-of-pocket maximum: once you hit it, the plan pays 100% for the rest of the year. Enrollment is year-round.
If your age and state put you on the expensive side of the tables above, run your own number with the Molli plan calculator.
Frequently asked questions
How much is health insurance for a freelancer in 2026? The average unsubsidized benchmark premium is about $625 per month for a 40-year-old, ranging from $401 in New Hampshire to $1,299 in Vermont. Costs rise with age: roughly $873 at 50 and $1,327 at 60.
Why did freelancer health insurance get so expensive in 2026? Two things compounded: insurers raised 2026 marketplace rates about 26% on average, and the enhanced ACA subsidies expired December 31, 2025, so many self-employed people now pay the full sticker price.
What state has the cheapest health insurance for the self-employed? By 2026 benchmark averages, New Hampshire ($401 per month at age 40), followed by Maryland ($414) and Minnesota ($448). Vermont, Wyoming, and West Virginia are the most expensive.
Do these prices include subsidies? No, they are pre-subsidy sticker prices. In 2026 households above roughly $62,600 (single) get no marketplace subsidy, so these figures are their actual cost.
¹ Savings vary by location, age, and plan selection. Based on comparison of Molli Pro plan rates to ACA Silver benchmark premiums.