The Hidden Costs of 'Catastrophic' Health Plans for Freelancers (And When to Avoid Them)
How to Protect Yourself
Catastrophic plans are often pitched as the ultimate low-cost solution for the self-employed. They feature the lowest monthly premiums available, but they hide a massive financial trap.
These plans have very high deductibles. In 2026, the ACA sets the maximum out-of-pocket limit for an individual at $10,600. For nearly every freelancer, a Bronze or Silver plan is a safer, smarter, and often cheaper choice.
1. The Major Downside: Forfeiting Financial Assistance Eligibility
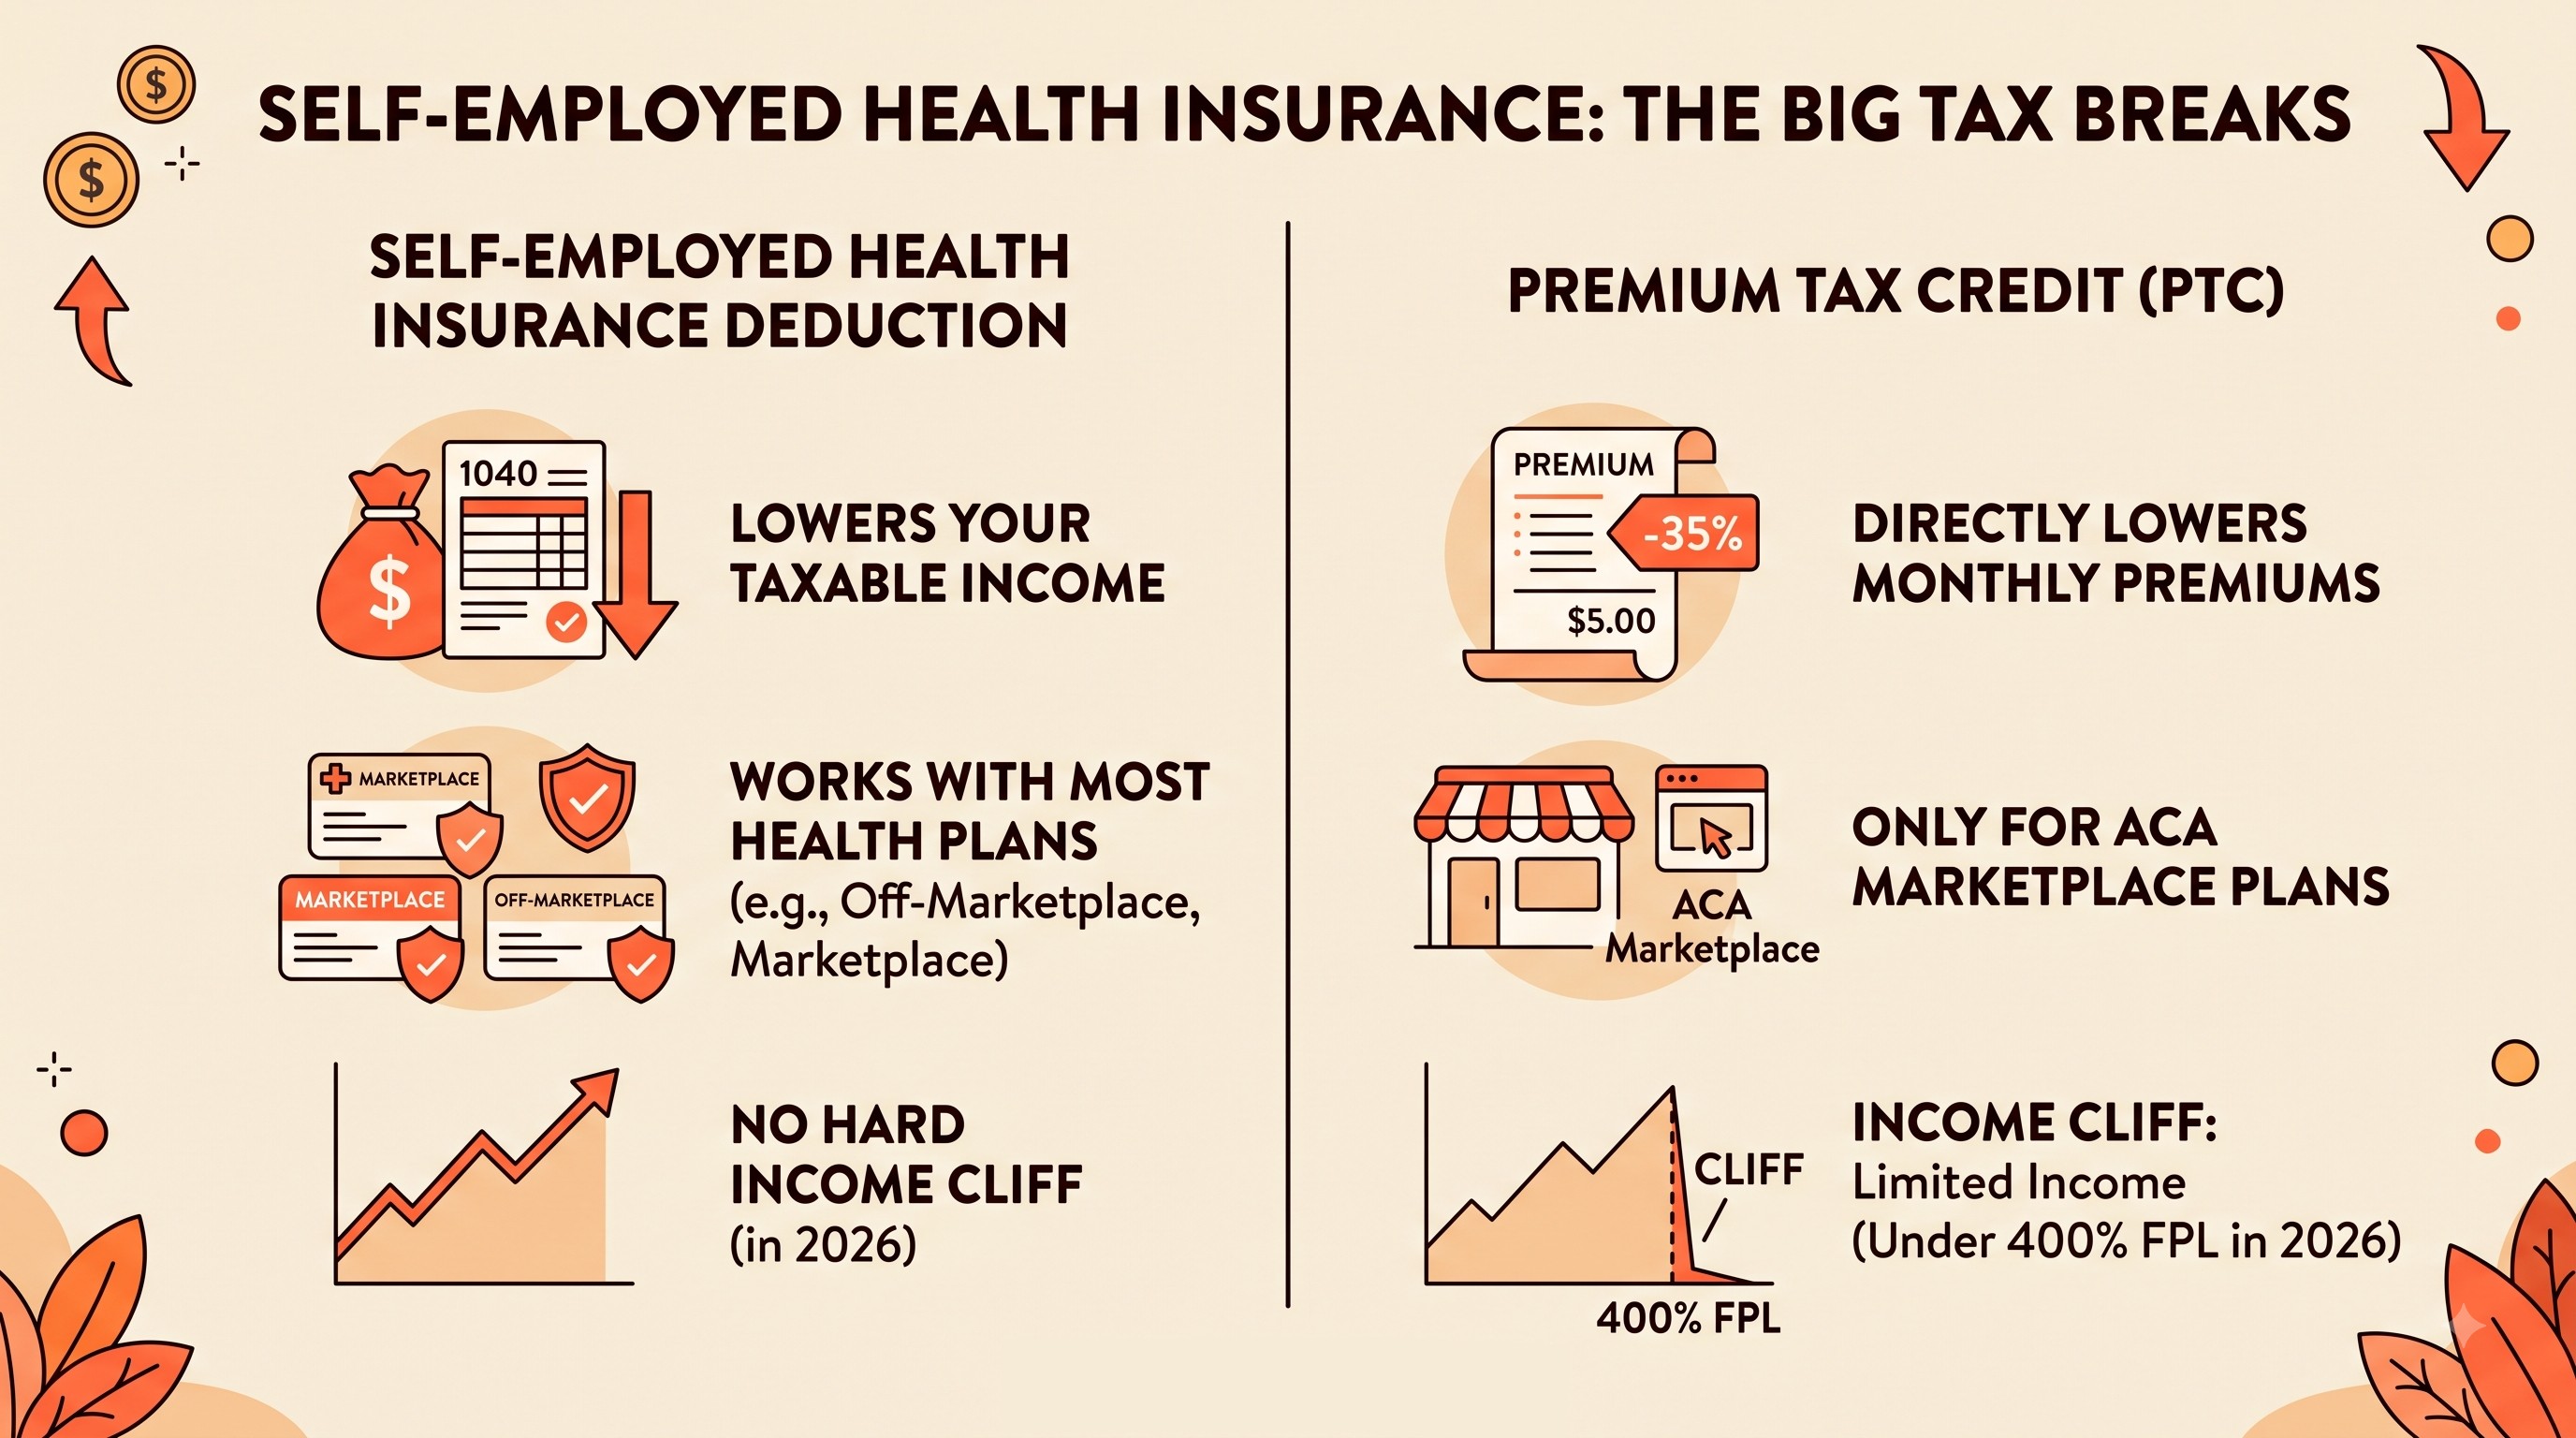
This is the single most critical reason to avoid a Catastrophic plan if you are eligible for financial assistance:
You CANNOT receive premium assistance with a Catastrophic Plan.
For the vast majority of independent contractors, premium assistance dramatically reduces the monthly premium on a Bronze or Silver plan. Even if the full-price Bronze plan looks more expensive than the Catastrophic plan, the available premium assistance applied to the Bronze or Silver plan will almost always make your final monthly payment lower than the Catastrophic premium.
The Financial Reality: You trade a small reduction in the monthly premium (Catastrophic) for the forfeiture of a large amount of federal assistance. The math rarely works in your favor.
2. The High-Deductible Trap
The purpose of a Catastrophic plan is to shield you only from "worst-case" scenarios.
- The Deductible is the Max: For 2026, you must pay $10,600 out-of-pocket for covered services before your plan begins to pay 100% of your bills. Unlike higher metal tiers, there is no gradual cost-sharing.
- Routine Care: While these plans must cover three primary care visits and all preventive care for free, every service beyond that (blood work, X-rays, generic prescriptions, specialists) is paid fully by you until you hit that high deductible.
3. Eligibility Restrictions
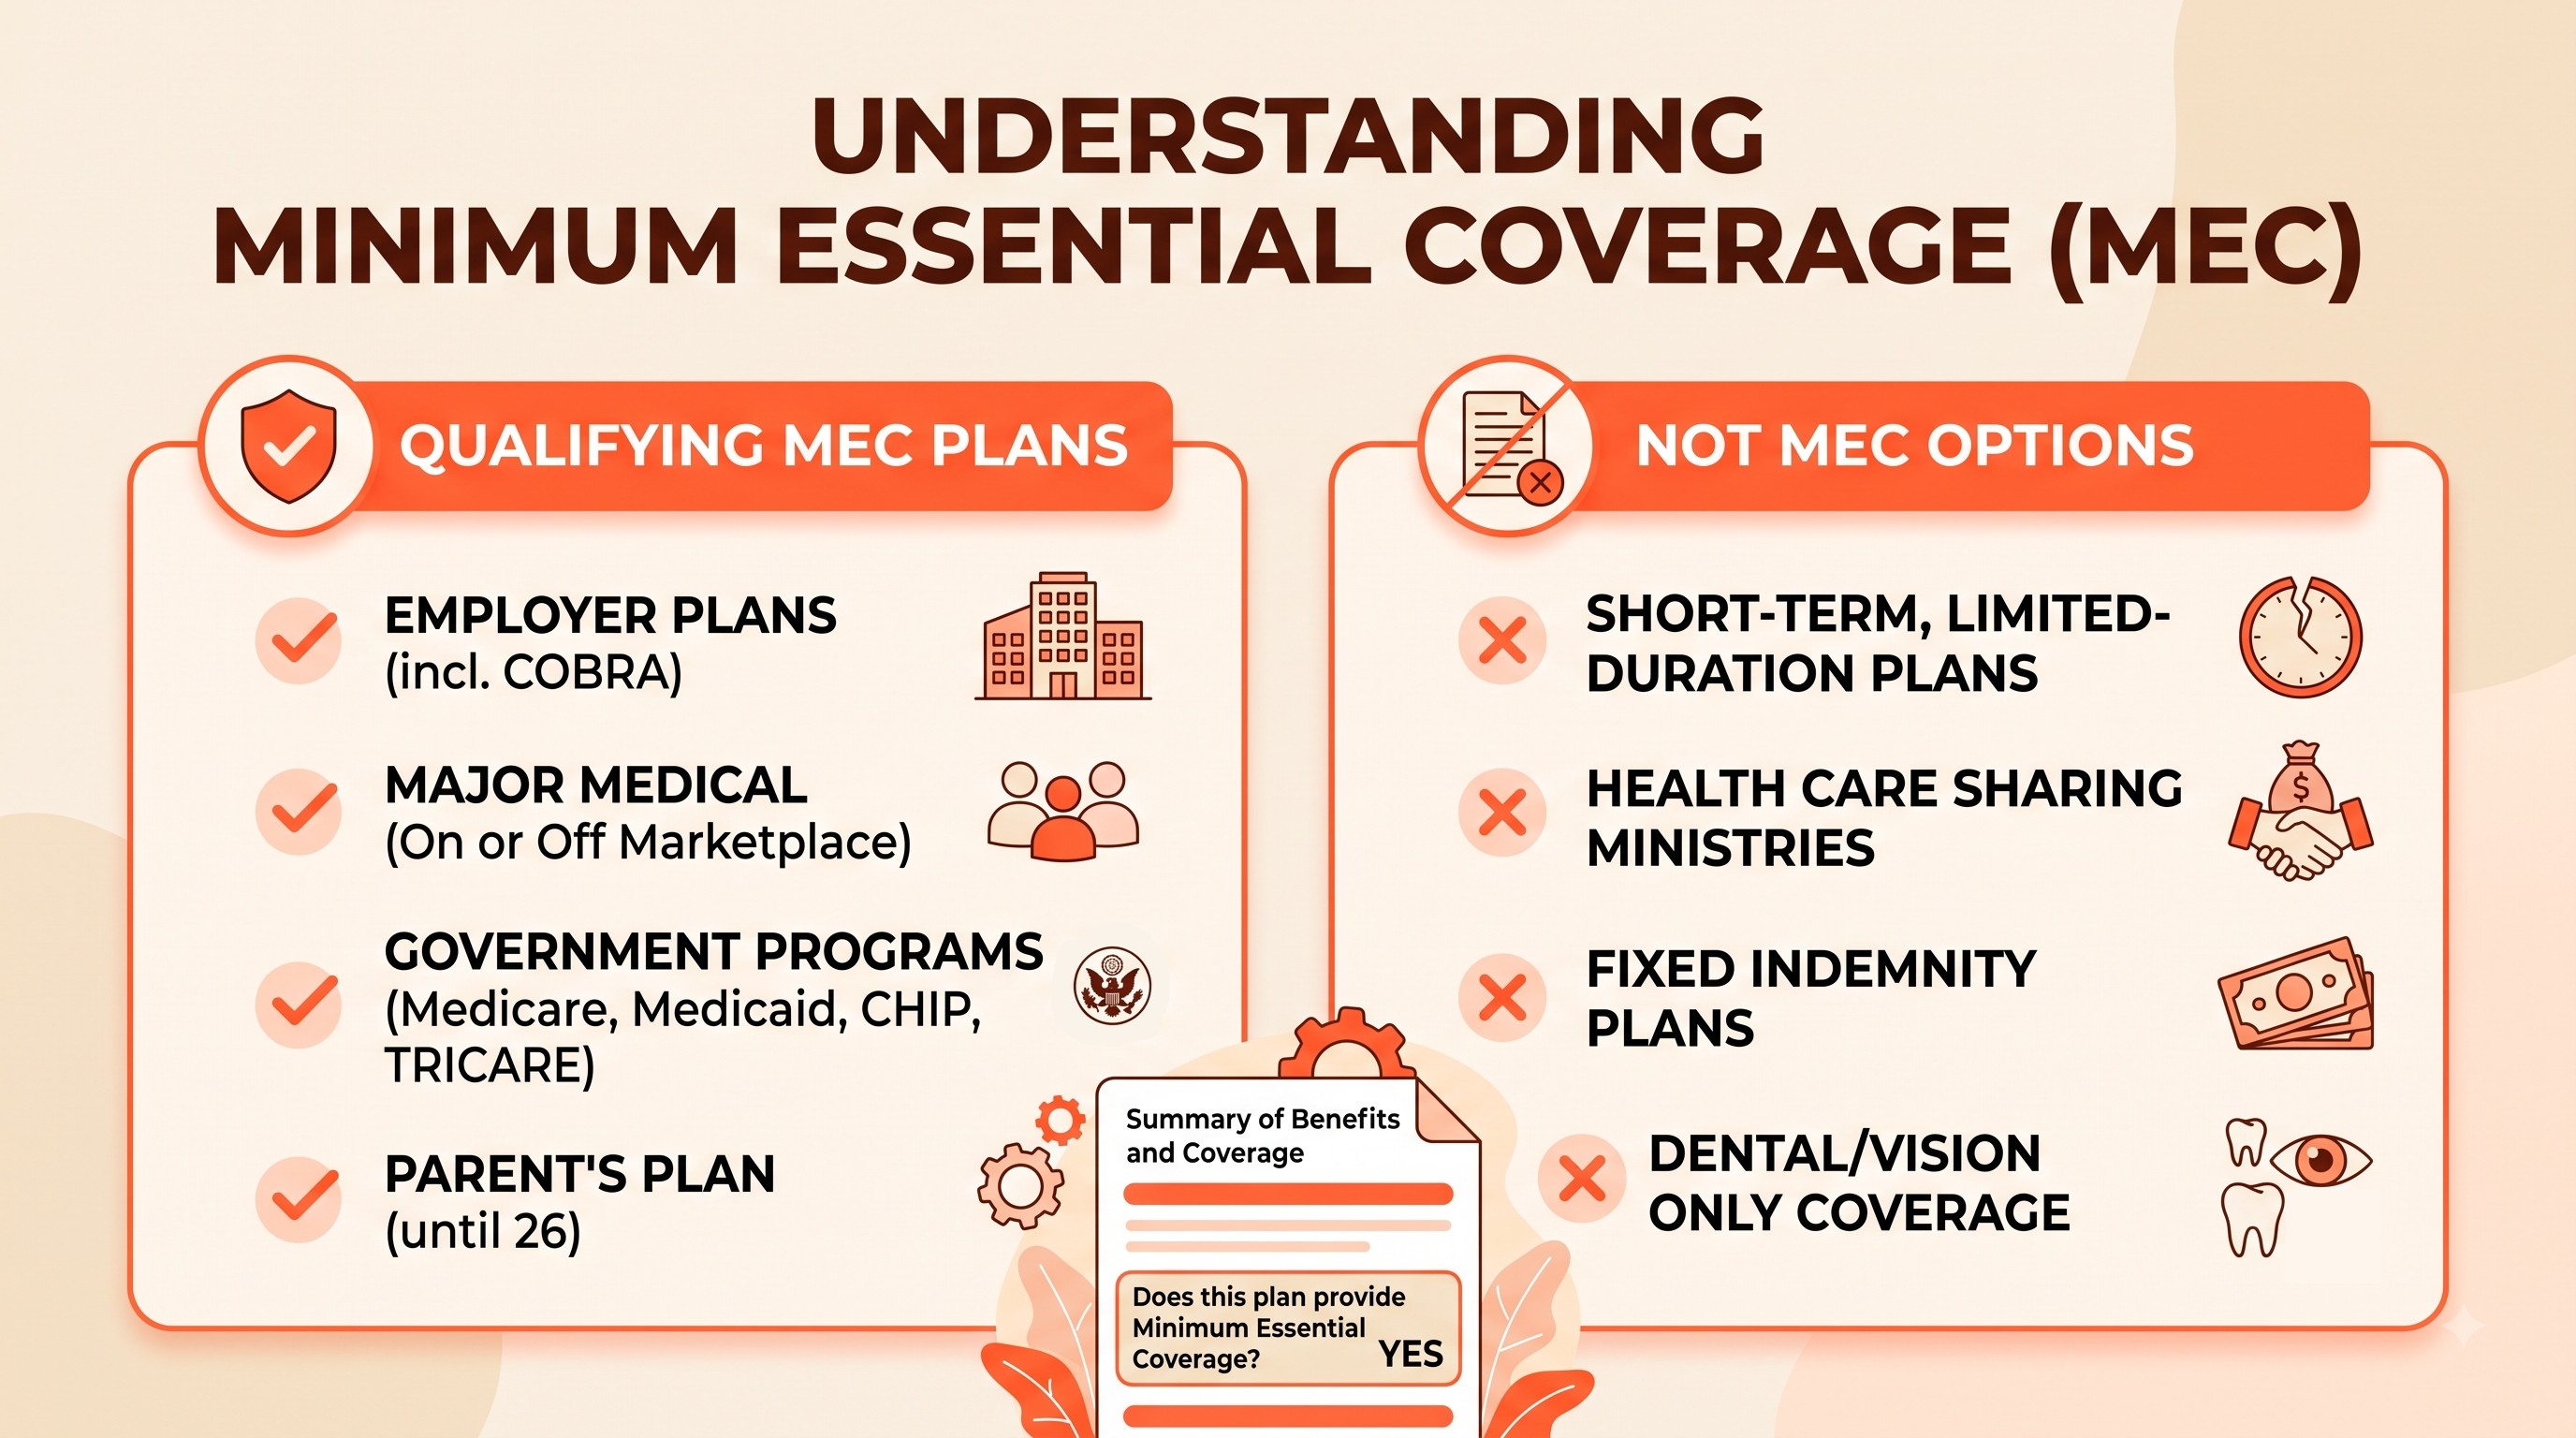
Catastrophic plans are not available to everyone. To enroll, you must be:
- Under the age of 30.
- OR qualify for a Hardship or Affordability Exemption from the Marketplace.
Molli’s Advice: The Safer, Smarter Alternatives
Molli Health is committed to guiding our clients toward plans that offer the best value and lowest financial risk.
We strongly recommend comparing the following options before considering a Catastrophic plan:
| Alternative option | Key advantage over catastrophic | Why it wins for freelancers |
|---|---|---|
| ACA Marketplace Silver plan | Eligible for premium assistance and cost-sharing reductions. | Cost-sharing reductions lower your deductible and copays, so your out-of-pocket maximum is often much lower than the catastrophic plan's $10,600. |
| ACA Marketplace Bronze plan | Eligible for premium assistance. | Offers a low premium (usually slightly higher than catastrophic) but has a lower deductible, and you can pair it with a dedicated savings account. |
| Molli (off-marketplace) | Predictable, transparent pricing and $0 everyday care. | An ACA-compliant major medical plan. ACA subsidies do not apply, but you get flat pricing (save up to 30% vs. ACA marketplace plans¹), $0 virtual primary care, a nationwide PPO network, and year-round enrollment. |
Where Molli Fits: if you qualify for meaningful ACA subsidies, a subsidized marketplace Bronze or Silver plan is usually the best value. If you do not qualify for subsidies, or you want predictable off-marketplace coverage, Molli is a strong alternative. Either way, both beat a catastrophic plan for most freelancers.
- $0 Virtual Primary Care: provides free routine virtual care, so you are not paying out of pocket for common visits the way you would on many traditional Bronze plans.
Don't trade security for a fraction of a monthly premium. The risk of being fully responsible for $10,600 in medical bills outweighs the benefit of the lowest premium. For the financially responsible freelancer, a subsidized Bronze or Silver plan, or an off-marketplace plan like Molli, is a smarter foundation than a catastrophic plan.
Stop guessing on risk. Use the Molli quote tool to see how much your monthly premium is reduced with assistance, proving that a safe plan can be the most affordable plan.
¹ Savings vary by location, age, and plan selection. Based on comparison of Molli Pro plan rates to ACA Silver benchmark premiums.